Implied Volatility Screener — Filter Current IV
Built, written, and reviewed by ConvexValue · Updated July 24, 2026
Build a current implied-volatility screener across U.S. option contracts, with liquidity controls and precise limits—without claiming an unvalidated IV-rank calculation.
Data cadence
The current options snapshot is ingested continuously and refreshed in the serving database about once a minute; implied volatility is a point-in-time snapshot field.
Plan requirements
The screen endpoint and current implied-volatility field are available on every cvforge data plan. Free includes 20 requests per hour; each screen response returns at most 500 rows.
Exact prompt
Build a current implied-volatility screener for U.S. options with cvApi.screen. Return underlying ticker, contract ticker, call or put, expiration, strike, fair_market_value, implied_volatility, day_volume, open_interest, delta, and underlying price. Start with implied_volatility at or above 0.60, open_interest at least 500 and day_volume at least 100. Sort by implied_volatility descending, cap the table at 100 rows, display IV as a percentage, and add controls for minimum IV, DTE, contract type, and minimum open interest. Show the snapshot refresh time. Label fair market value as a non-executable estimate. Call this current IV, never IV rank or IV percentile, and label the result research only.
Fields used
underlying_ticker, ticker, contract_type, expiration_date, strike_price, fair_market_value, implied_volatility, day_volume, open_interest, delta, underlying_price
What the filter actually measures
This template filters the implied_volatility value on the current options
snapshot. The server applies the threshold across contracts; the app formats
the decimal as a percentage and adds controls so you can tighten liquidity,
expiration, and contract-type constraints without rewriting the page.
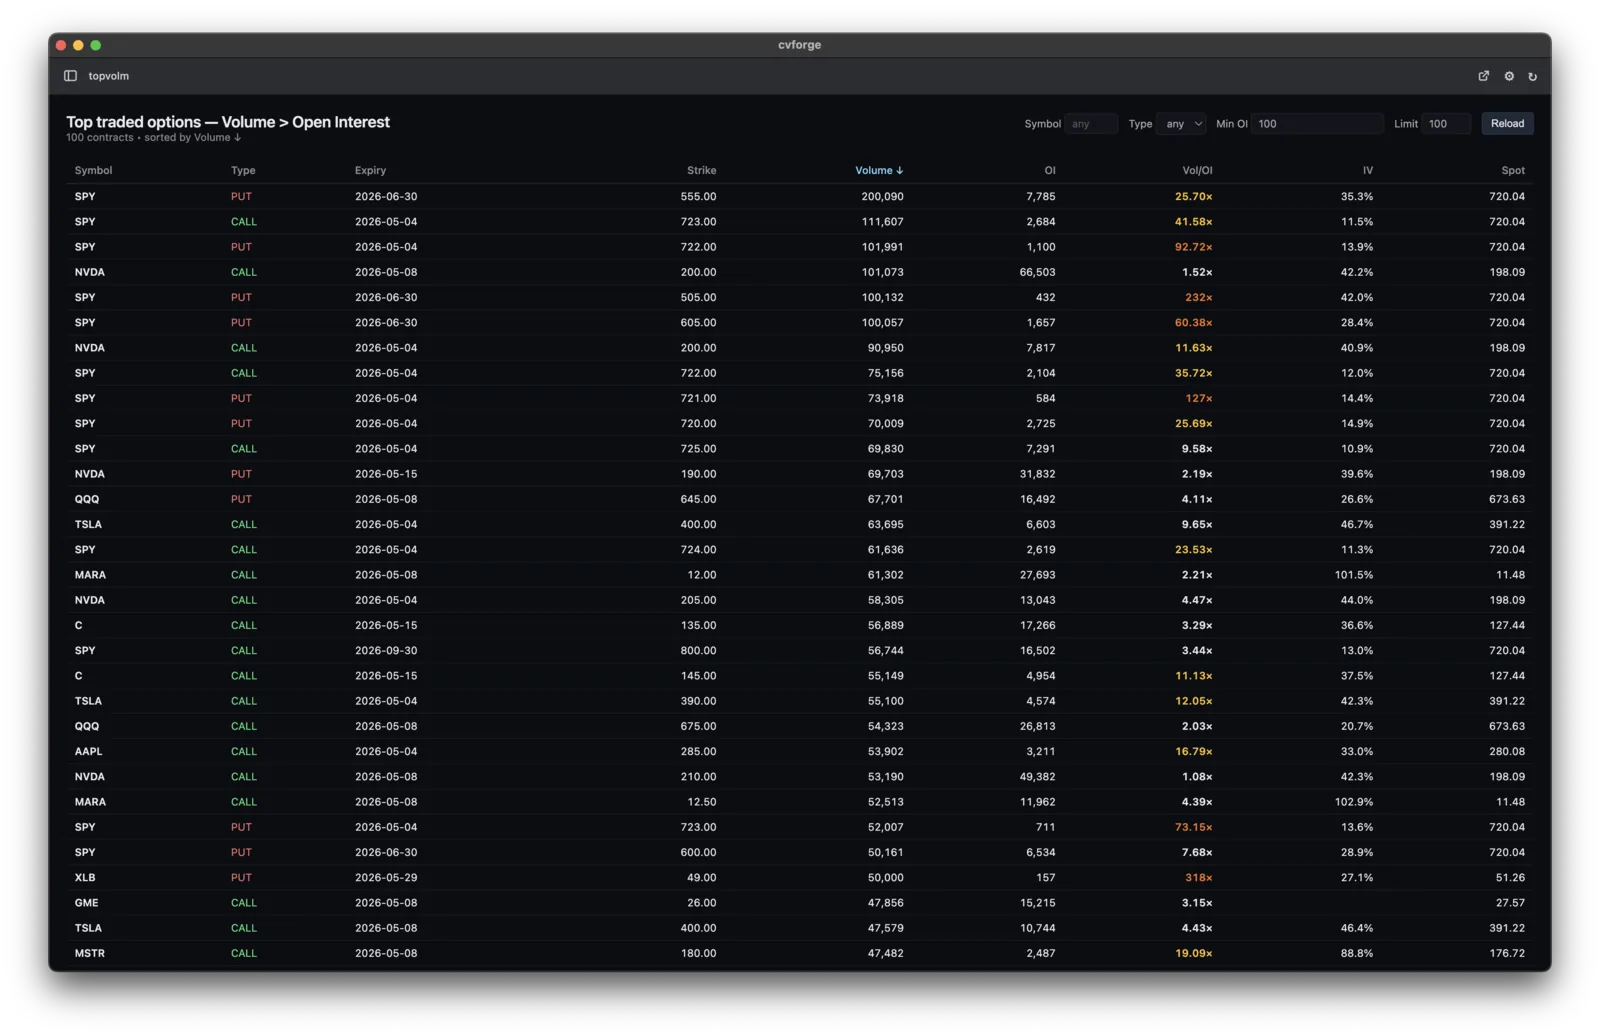
The screenshot shows the same cvforge-built contract table surface with the IV column beside volume, open interest, expiration, strike, and spot. A separate cvforge IV-surface build is also available in the IV surface walkthrough, but that visualization answers a different question from a market-wide filter.
Current IV is not IV rank
IV rank needs a defined historical series, lookback window, aggregation rule, and missing-data policy. This template claims none of those. A contract with 60% current IV passes a 60% threshold; the result does not tell you where that value sits in its own historical range.
That distinction is important for reproducibility. If you need a different current threshold, delta range, expiration window, or liquidity rule, ask the agent to edit those explicit conditions. Do not ask it to relabel current IV as a historical statistic.
Useful edits to ask for next
- “Keep only contracts with absolute delta between 0.20 and 0.40.”
- “Add a 14–60 DTE window and require session volume of at least 500.”
- “Group by underlying and show the median current IV of the returned contracts.”
- “Add an underlying-price minimum and a ticker allowlist.”
See the full Options Screener API contract or return to the custom options screener for other templates.
Limitations
- Current implied volatility is not IV rank or IV percentile; this template does not compare the value with a historical IV series.
- cvforge provides Massive fair market value estimates, not option bid/ask quotes, midpoint, NBBO, or last trades; this template cannot measure the quoted spread or executable liquidity.
- A high current IV value does not predict direction or guarantee that an option is rich or cheap.
- The template is for research and education, not investment advice or an order-execution tool.
Search focus: implied volatility screener. Related: implied vol screener, current IV options screener, high implied volatility options filter.